Financial Market Products (HSC SSCE Economics): Revision Notes
📚Revision Notes
Financial Market Products
Introduction to financial market products
Financial markets offer a diverse range of products designed to meet the varying needs of both lenders (investors) and borrowers. These products differ across three critical dimensions:
- Risk: The likelihood of financial loss
- Return: The potential profit or income generated
- Liquidity: How easily the asset can be converted to cash
Understanding these characteristics helps participants choose products that match their financial goals and risk tolerance.
Note
The three dimensions of risk, return, and liquidity are interconnected. Generally, higher potential returns come with higher risk, and highly liquid assets often offer lower returns than less liquid alternatives.
Consumer credit
Consumer credit allows individuals to purchase goods and services now and pay for them later. Essentially, it enables people to access their expected future income to fund current consumption.
Credit cards
Credit cards are the most widely used form of consumer credit. They allow consumers to buy goods immediately and repay the borrowed amount with interest at a later date.
Providers include:
- Banks and credit unions
- Retailers and service providers (e.g. Woolworths, Jetstar, Virgin) partnering with card companies like Mastercard and Visa
- Independent credit card companies such as American Express and Diners Club
Interest rates: Generally range between 10% and 20% per annum.
Personal loans
Banks and credit unions offer personal loans for various consumer purposes. These loans provide a lump sum that is repaid in regular instalments with interest.
Interest rates: Typically 10-15% per annum, higher than housing loans due to increased risk.
Understanding interest rate variation
Important
The differences in interest rates across financial products reflect the risk to the lender. When lenders face a higher probability that borrowers will not repay (known as default risk), they charge higher interest rates as compensation. This explains why unsecured consumer credit products carry higher rates than secured housing loans.
Housing loans
Housing loans, commonly called mortgages, are long-term loans used to purchase property. Borrowers make periodic repayments that include both principal and interest over the loan term.
Providers:
- Banks
- Mortgage originators such as Aussie and RAMS
Key characteristics:
Housing loans are typically secured loans—the property itself serves as collateral. If borrowers default on repayments, lenders can sell the property to recover their losses. This security reduces risk for lenders.
Interest rates: Usually 1-2 percentage points above the Reserve Bank cash rate, significantly lower than unsecured consumer credit.
Market scale: In mid-2019, Australian households had outstanding housing debt exceeding $1.1 trillion for owner-occupied housing alone.
Note
Competition in the home loan market declined following the 2008 global financial crisis, when traditional banks acquired many non-bank lenders, reducing market diversity. This consolidation reduced the number of competing providers in the market.
Business loans
Business loans provide debt financing that enables businesses to invest in their operations—purchasing new technology, expanding premises, or funding working capital needs.
Interest rate structure:
The rates businesses pay depend significantly on their size and risk profile:
- Large corporations: Pay rates similar to housing loans
- Small businesses: May pay up to 5 percentage points more than housing loan rates
This substantial difference reflects several factors:
- Higher default risk for smaller businesses
- Lack of substantial assets to secure the loan
- Greater administrative costs relative to loan size
Providers:
- Finance companies and banks (particularly for small businesses)
- Investment banks (for larger corporations)
Market scale: Australian businesses had approximately $950 billion in outstanding debt in mid-2019.
Short-term money market
The short-term money market connects participants with temporary cash shortages to those with temporary surpluses. It facilitates efficient allocation of short-term funds in the economy.
Mechanism:
Institutions with surplus funds (such as banks) issue various forms of debt securities to those needing short-term finance. Common instruments include:
- Bank bills
- Promissory notes
Defining feature: All securities in this market have maturity dates of less than one year, distinguishing them from longer-term debt instruments.
Bonds (fixed-income securities)
Bonds are longer-term debt securities that provide investors with predictable income streams. They represent loans made to governments or large corporations.
Who issues bonds:
- Government (Commonwealth and state)
- Large corporations
- Major banks
Key structural features:
- Face value: The principal amount of the debt—the initial loan amount that will be repaid at maturity
- Coupon payments: Regular fixed payments made to bondholders, functioning like interest payments
- Date of maturity: The end of the bond period when the face value is repaid to the bondholder
Market scale in Australia (2019):
- Government bonds outstanding: $797 billion
- Corporate bonds outstanding: $605 billion
Note
The value of Commonwealth bonds decreased during the 1990s and 2000s as budget surpluses allowed debt repayment, but increased sharply from 2008 when government borrowing rose in response to the global financial crisis.
Understanding bond mechanics
Example
Worked Example: Bond Returns and Yield
Consider a large company that issues a 10-year corporate bond with:
- Face value: $1,000,000
- Annual coupon payment: $50,000
- Initial sale price: $1,000,000
For the bondholder:
- Receives $50,000 annually (5% of face value)
- After 10 years, receives the $1,000,000 face value back
- Total return: $500,000 in coupon payments plus the $1,000,000 principal
Calculating yield:
Bond yield represents the rate of return and is calculated as:
In our example:
The inverse relationship: bond prices and interest rates
Important
Critical Concept: Bond Prices and Interest Rates Move in Opposite Directions
A crucial concept for understanding bonds is their inverse relationship with economy-wide interest rates:
When interest rates across the economy rise:
- New buyers demand higher yields to compensate for alternative investment opportunities
- Since coupon payments are fixed, yield can only increase through a lower bond price
- Result: Bond prices fall
When interest rates across the economy fall:
- Existing bonds become more attractive with their fixed coupon payments
- Demand for existing bonds increases
- Result: Bond prices rise
This relationship means bond prices fluctuate inversely with interest rate movements after issuance.
Secondary market trading:
Bonds can be bought and sold in the bond market after initial issue. This provides liquidity—bondholders can sell their bonds before maturity if they need to convert their investment to cash.
Financial futures and options
These financial instruments are contracts to trade underlying financial assets (such as shares, bonds, or currencies) at a future date for a price agreed upon today. They serve primarily as risk management tools.
Futures contracts
Purpose: Allow investors and businesses to protect themselves against adverse movements in:
- Interest rates
- Exchange rates
- Share prices
Mechanism: Both parties agree now on the price, currency, and terms for a transaction that will occur at a specified future date. Both parties are obligated to complete the transaction when the date arrives.
Example
Worked Example: Currency Futures
An Australian company expecting to receive US$1 million in six months could enter a futures contract to sell US dollars at a fixed exchange rate, protecting against potential depreciation of the US dollar.
This protects the company from exchange rate risk, ensuring they know exactly how many Australian dollars they will receive regardless of currency fluctuations.
Options contracts
Key distinction: Options give the holder the right but not the obligation to complete a transaction.
Flexibility: The holder can:
- Exercise the option (complete the transaction if favorable), or
- Let the option expire without action (if conditions are unfavorable)
Note
This flexibility comes at a cost—option buyers pay a premium for this right, while futures contracts typically have no upfront cost.
Foreign exchange (forex) market
The foreign exchange market facilitates the buying and selling of currencies. It is essential for international trade and investment.
Market participants:
- Individuals purchasing foreign currency for travel
- Businesses paying for imports or receiving export revenue
- Investors buying foreign assets
- Financial institutions managing currency exposures
Operating characteristics:
The forex market operates 24 hours a day, reflecting:
- Global distribution of trading across time zones
- Continuous need for currency exchange in international commerce
Australian context:
Australia has large and sophisticated foreign exchange markets:
- Daily Australian forex market transactions averaged US$134.8 billion in April 2016
- The Australian dollar is the fifth most traded currency globally
- This reflects Australia's integration into the global economy and its commodity export base
Superannuation
Since the early 1990s, Australian employers have been legally required to contribute to individual employees' superannuation accounts. This system of compulsory retirement savings makes superannuation central to Australia's financial markets.
Scale and global significance
Note
With approximately $3.5 trillion under management as of March 2019, Australia has the fourth largest funds management industry in the world—remarkable for a nation of just over 25 million people.
How superannuation works
Contribution phase:
- Employers contribute a percentage of wages to employees' superannuation accounts
- The superannuation guarantee was 9.5% in 2019
- Government plans to gradually increase this to 12% by 2025
Investment phase:
- Superannuation funds invest contributions across various financial products
- Investments include Australian and international shares, bonds, property, and other assets
Retirement phase:
- When employees retire, accumulated funds provide retirement income
- Can be accessed as regular payments or a lump sum
Investment allocation
Superannuation funds diversify their investments across multiple asset classes to balance risk and return:
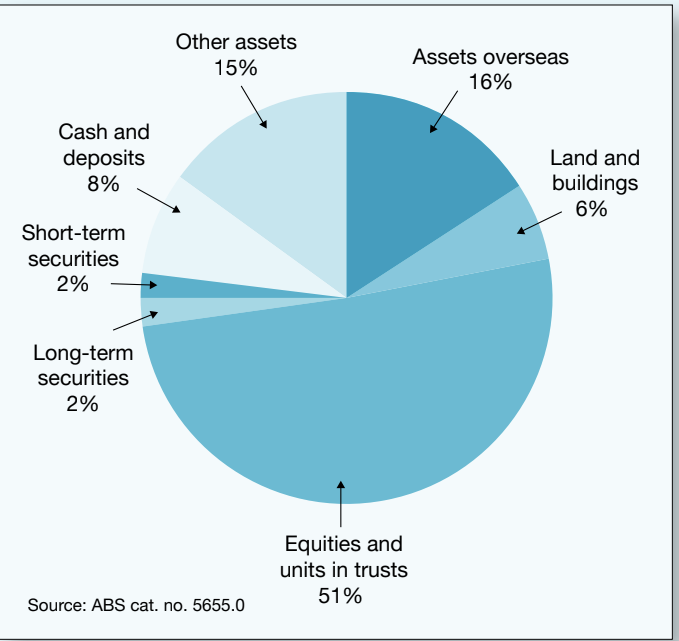
The asset allocation shows that:
- Equities and units in trusts dominate at 51%, reflecting the long-term investment horizon and growth focus
- Assets overseas comprise 16%, providing international diversification
- Other assets make up 15%
- Cash and deposits account for 8%, providing liquidity
- Land and buildings represent 6%
- Securities (both short-term and long-term) total 4%
Economic significance
Benefits for individuals:
- Retirement income security: Reduces reliance on the age pension
- Access to sophisticated investments: Allows indirect ownership of shares and complex financial products typically inaccessible to individual investors
- Higher returns: Equity investments generally provide better long-term returns than simple bank deposits
Benefits for the economy:
- Capital formation: Creates a large pool of investment funds for productive use
- Housing market support: Funds can be lent to financial institutions, which then provide mortgages to households
- Business investment: Direct investment in new share issues provides capital for business expansion
- Economic growth: Channeling savings into productive investment drives economic growth and job creation
Volatility and risk
Important
Because superannuation is heavily invested in equities (51%), share market movements are the primary driver of superannuation balance changes. This means:
- Superannuation balances can fluctuate significantly in the short term
- Long-term returns are generally higher but come with increased volatility
- The long investment horizon (decades until retirement) allows recovery from market downturns
Regulation
The Australian Prudential Regulation Authority (APRA) regulates the superannuation industry. This oversight is crucial given:
- The compulsory nature of contributions
- The importance of retirement savings to individuals' financial security
- The systemic importance of superannuation to the broader economy
Remember!
Summary
Key Points to Remember:
Core principles of financial market products:
- Financial products vary across risk, return, and liquidity dimensions—higher returns generally require accepting higher risk or lower liquidity
- Interest rates reflect default risk: Secured loans (housing) carry lower rates than unsecured loans (personal loans, credit cards) because lenders face less risk
- Bonds and interest rates move inversely: When economy-wide interest rates rise, existing bond prices fall, and vice versa, because coupon payments are fixed
- Australia's superannuation system is globally significant: With $3.5 trillion under management, it represents the world's fourth largest funds management industry
- Financial markets serve different time horizons: From short-term (money market securities under one year) to long-term (bonds, housing loans spanning decades)
Essential terminology:
- Credit: Loans extended for consumption and investment purposes
- Secured loan: Loan backed by collateral such as property, reducing lender risk
- Default: Failure to meet loan repayment obligations
- Bond yield: Rate of return on a bond, calculated as coupon payment divided by bond price
- Coupon payment: Fixed periodic payment to bondholders
- Face value: The principal amount of a bond, repaid at maturity
- Maturity: The date when a bond's principal is repaid
- Futures: Contracts creating an obligation to complete a transaction at a future date
- Options: Contracts providing the right, but not the obligation, to complete a future transaction
- Forex market: Market for buying and selling currencies, operating 24 hours daily