Primary and Secondary Financial Markets (HSC SSCE Economics): Revision Notes
📚Revision Notes
Primary and Secondary Financial Markets
Understanding financial market structure
Financial markets can be divided into two fundamental categories based on whether securities are being created for the first time or traded between investors. This distinction is crucial for understanding how companies raise capital and how investors trade financial assets.
Note
The Australian financial sector is substantial, employing approximately 450,000 people and contributing around `$`170 billion to GDP in 2018–19. Understanding how these markets function is essential for grasping broader economic activity.
Primary financial markets
Primary financial markets are where new financial assets, called securities, are created and sold for the first time. When a business needs to raise funds, it can issue new securities through a primary market.
In a primary market transaction, money flows directly from investors to the company issuing the securities. The company receives this capital to use for business expansion, operations, or other purposes.
Securities are financial instruments (such as shares or bonds) that provide the holder with a claim over real assets or a future income stream.
How primary markets work
Companies can raise funds in primary markets through two main methods:
- Issuing debt securities: The company borrows money by selling bonds or other debt instruments to investors. This creates a legal obligation to repay the borrowed amount plus interest.
- Selling new shares: The company expands ownership by issuing additional shares. This brings in new equity capital without creating debt.
Example
Primary Market Transaction: Westpac Bank Share Issue
When Westpac Bank issues a new batch of shares to the public for the first time, this is a primary market transaction. The money paid by investors goes directly to Westpac, which can then use these funds for lending, expansion, or other business activities.
Secondary financial markets
Secondary financial markets involve the trading of financial assets that were originally issued on a primary market at some earlier time. These are markets for existing securities.
Important
The crucial distinction is that companies whose securities trade on secondary markets receive no money from these transactions. Instead, money flows between investors – from the buyer to the seller.
How secondary markets work
Most financial market activity occurs on secondary markets. When you buy shares in Commonwealth Bank through the stock exchange, you're not buying them from the bank itself. You're buying from another investor who previously owned those shares. Commonwealth Bank receives no funds from this transaction.
Why secondary markets matter
Although companies don't receive money from secondary market trades, these markets serve vital economic functions:
- They provide liquidity, allowing investors to sell their securities when needed
- They establish market prices for securities through supply and demand
- They make primary markets more attractive by ensuring investors can later sell their holdings
- They facilitate efficient capital allocation across the economy
Note
Secondary markets don't directly provide capital to companies, but they're essential for making primary markets work effectively. Without the ability to resell securities, investors would be far less willing to purchase them in the first place.
The Australian Securities Exchange (ASX)
The Australian Securities Exchange (ASX) is Australia's major share market where most trading in public company shares occurs. It functions as both a primary market (for new share issues) and a secondary market (for trading existing shares).
The ASX demonstrates that markets don't require physical locations. Most trading occurs through interconnected computer systems rather than on a physical trading floor.
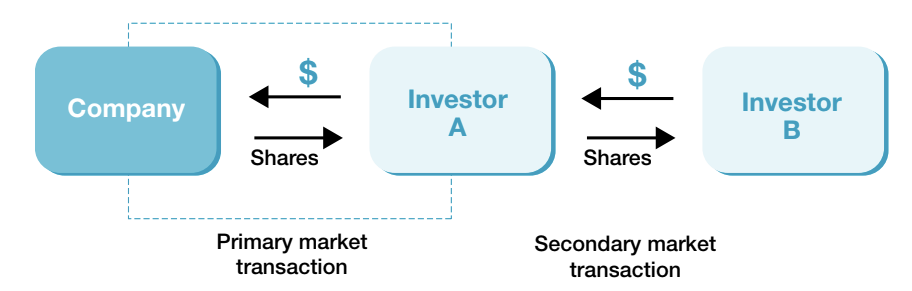
The diagram above illustrates the key difference between primary and secondary markets. In the primary market (left), the company receives money directly from Investor A in exchange for newly issued shares. In the secondary market (right), Investor A sells existing shares to Investor B, with money flowing between investors rather than to the company.
The four main types of financial markets
Financial markets can be further categorized by the type of asset being traded. Four main categories exist across economies worldwide:
Share or equity market
This is where ownership stakes in companies are issued and traded. When you buy shares, you're purchasing a portion of ownership in that company, entitling you to a share of profits (dividends) and potential capital gains.
Debt market
This market facilitates the borrowing and lending of money. Debt securities such as bonds are traded here. These represent loans where the borrower agrees to repay the principal plus interest over time.
Derivatives market
Derivatives are financial assets whose value is based on (derived from) the value of other underlying assets. Examples include options and futures contracts. These instruments allow investors to hedge risks or speculate on price movements.
Note
Derivatives don't represent direct ownership or lending. Instead, they're contracts whose value depends on the performance of underlying assets like shares, bonds, commodities, or currencies.
Foreign exchange market
This market enables the exchange of currencies. Financial assets defined in one country's currency can be exchanged for assets in another currency. This market is essential for international trade and investment.
Financial intermediaries: bridging savers and borrowers
Financial intermediaries are institutions that collect funds from individuals or firms who have excess savings, then lend these funds to others who need capital. They create a bridge between savers and borrowers in the economy.
All financial intermediaries perform the same basic economic function: channeling surplus savings from net savers to net borrowers. However, different types of intermediaries specialize in various services and serve different market segments.
Banks
Banks remain the largest and most important financial intermediaries. They offer comprehensive services including:
- Accepting deposits (savings accounts)
- Making loans (mortgages, business loans, personal loans)
- Issuing credit cards
- Providing payment services
- Offering financial advice
- Facilitating international transactions
Non-bank financial intermediaries
The financial sector has evolved significantly, with many services once exclusive to banks now offered by other institutions. Key types include:
Note
Finance companies borrow funds from the public or other financial institutions, then lend these funds to households and businesses at higher interest rates.
Fintech companies represent a growing category – these are financial services businesses using digital technologies (like artificial intelligence or blockchain) to improve efficiency or deliver new services. Some fintechs have developed automated loan assessment processes.
Investment banks focus on serving large corporate clients. They provide short-term borrowing and lending for major companies, offer advisory services for corporate transactions (like mergers and takeovers), and trade securities on their own accounts.
Credit unions are non-profit cooperative organizations. Members, who typically share a common bond (such as working in the same industry or living in the same area), can deposit and borrow money. Any profits are returned to members.
Permanent building societies traditionally focused on home loans, accepting public deposits and providing mortgage financing. While they can offer other loan types, their operations are partly regulated by state governments.
Note
Mortgage originators (such as Aussie Home Loans and RAMS) specialize in home loans. These non-bank lenders grew rapidly in the 1990s and 2000s by offering competitive interest rates and flexible repayment options. However, during the global financial crisis, many struggled to access funding and were subsequently acquired by traditional banks.
Superannuation funds collect contributions from employees and employers, investing these funds to provide retirement income. Since compulsory superannuation was introduced in the early 1990s, this sector has grown substantially. Superannuation funds are now major investors in Australian and international financial markets.
Exam relevance
Understanding primary and secondary markets is fundamental for analyzing:
- How companies raise capital for investment
- The relationship between financial markets and economic growth
- The role of liquidity in efficient capital allocation
- How financial market disruptions affect the broader economy
Important
When answering exam questions about financial markets, clearly distinguish between primary markets (where companies raise new capital) and secondary markets (where existing securities are traded). Explain the economic significance of each market type and how they interact.
Summary
Key Points to Remember:
- Primary markets create new securities, with funds flowing directly to the issuing company
- Secondary markets trade existing securities between investors, with no funds going to companies
- Securities are financial instruments providing claims over assets or income streams
- The ASX is Australia's main share market, operating both primary and secondary markets
- Four main market types exist: share/equity (ownership), debt (lending/borrowing), derivatives (based on other assets), and foreign exchange (currency trading)
- Financial intermediaries bridge savers and borrowers, including banks, fintech companies, credit unions, building societies, mortgage originators, and superannuation funds
- Most financial market trading occurs on secondary markets, even though primary markets are essential for companies to raise new capital