Regulation of Financial Markets (HSC SSCE Economics): Revision Notes
📚Revision Notes
Regulation of Financial Markets
Financial markets must remain stable for the economy to function effectively. When the flow of funds from savers to borrowers through financial intermediaries is disrupted, serious consequences can follow. Households may lose their savings, businesses can face bankruptcy, and economic confidence across the entire economy may be undermined, leading to reduced economic growth.
Government regulation of financial markets is therefore a key priority of economic policy. This regulation aims to maintain stability, protect consumers and investors, and ensure the financial system operates efficiently.
Why regulation matters
Financial market instability creates significant risks. If financial institutions fail, depositors can lose their savings and businesses may be unable to access the credit they need to operate. During periods of instability, confidence throughout the economy can collapse, causing businesses to reduce investment and households to cut consumption. This can trigger broader economic problems, including recession.
Important
The global financial crisis of 2008 demonstrated these risks dramatically. Major financial institutions collapsed, share markets crashed worldwide, and many economies fell into deep recession. The crisis showed that effective regulation is essential to prevent such catastrophic outcomes.
International regulation of financial markets
Global financial markets operate with less regulation than domestic markets, but several international organizations coordinate regulatory approaches across countries.
Bank for International Settlements (BIS): This international organization helps central banks, such as the Reserve Bank of Australia, promote financial stability through appropriate market regulations. The BIS facilitates cooperation between central banks worldwide.
Basel Committee: A related organization to the BIS, the Basel Committee sets standards for banking regulations globally. Its objective is to promote effective and uniform financial regulatory systems around the world, ensuring banks in different countries operate under similar safety requirements.
International Monetary Fund (IMF): The IMF oversees the general stability of the international financial system. It monitors economies and markets, and assists countries experiencing difficulty meeting their international financial obligations.
Note
Other international bodies: The International Organisation of Securities Commission coordinates regulation of share markets, while the International Association of Insurance Supervisors does the same for insurance markets.
These international organizations help ensure that financial market problems in one country do not easily spread to others, and that regulatory standards remain reasonably consistent across different countries.
Australia's regulatory framework
In Australia, four government bodies share responsibility for regulating and supervising the financial system. Each has distinct but complementary roles: the Reserve Bank of Australia (RBA), Australian Prudential Regulation Authority (APRA), Australian Securities and Investments Commission (ASIC), and Australian Treasury.
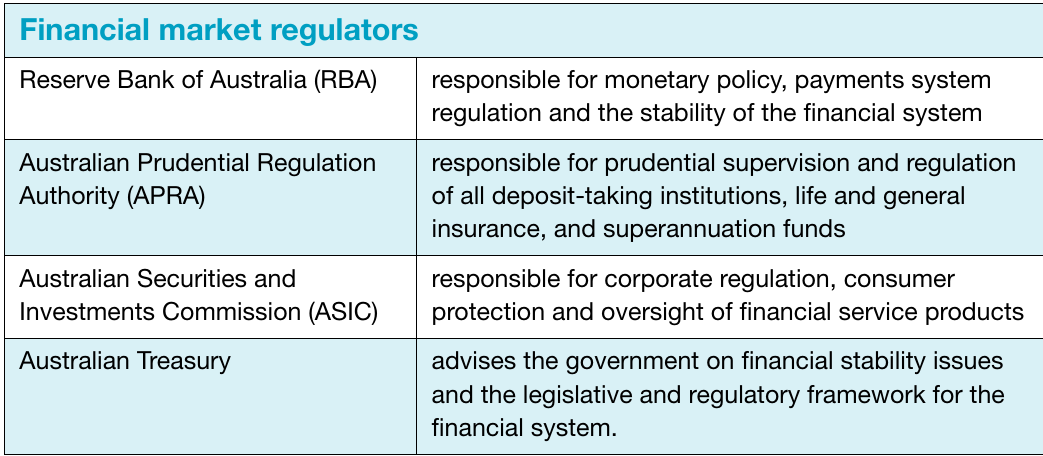
Council of Financial Regulators
The Council of Financial Regulators coordinates financial market regulation among its four members: the RBA, APRA, ASIC, and Treasury. This informal body enables information sharing and coordination of advice between the regulators. It does not have regulatory powers separate from its individual members.
Note
During the global financial crisis in 2008, the Council produced a joint Memorandum of Understanding outlining how the organizations would respond to the crisis. This coordination proved valuable in managing Australia's response to the international financial turmoil.
Historical development of financial regulation
Australia's current regulatory framework has evolved significantly over recent decades through several major reforms.
Financial deregulation (1980s)
During the early to mid-1980s, the government deregulated the financial sector. This involved removing many government controls over the finance sector, exposing the industry to greater influence from domestic and global market forces. Before deregulation, the government had imposed strict controls on interest rates, lending practices, and foreign bank entry.
Wallis Committee reforms (late 1990s)
The structure of regulatory responsibilities between the four agencies was established in the late 1990s following an influential inquiry known as the Wallis Committee. This committee recommended significant changes to regulation to keep pace with financial sector developments, including:
- New technologies changing how financial services were delivered
- Increased competition between financial institutions
- The breakdown of old distinctions between different types of institutions (for example, banks increasingly offering insurance products)
These reforms represented the largest changes to financial sector regulation since deregulation in the 1980s.
Global Financial Crisis responses (2008-2009)
The global financial crisis put Australia's regulatory framework under greater scrutiny. While Australia's financial system weathered the crisis better than many other countries, several regulatory changes were implemented:
Short selling ban: ASIC imposed an interim ban on "short selling" - a practice where investors sell shares they do not own, hoping to buy them later at a lower price. This ban was lifted in May 2009.
Government guarantees: The government guaranteed 15 million deposit accounts (worth $800 billion) in banks, credit unions, and building societies. Bank deposits up to $250,000 per person in any given bank remain guaranteed by the government today. This prevented depositors from panicking and withdrawing their funds during the crisis.
Future of Financial Advice reforms: Introduced in 2013, this reform package banned financial advisers from receiving commissions from product providers and imposed a legal duty on advisers to put their clients' interests first.
Murray Review (2014)
The Financial System Inquiry (known as the Murray Review) assessed Australia's financial system and made recommendations to improve its robustness against international developments, technological change, and demographic trends like population aging.
Key recommendations included:
- Increasing the capital that banks must hold against their loan assets to match the safest banks globally
- Making regulatory requirements more competitively neutral to reduce advantages enjoyed by big banks over smaller competitors
- Strengthening consumer protection laws on financial products
Note
However, little legislative progress occurred to implement these recommendations. One exception was 2016 laws banning excessive credit card surcharges.
Royal Commission (2018-2019)
In 2018, the government established a Royal Commission into Misconduct in the Banking, Superannuation and Financial Services Industry. This followed several high-profile bank scandals, including:
- Alleged rigging of the bank bill swap rate (a key interest rate benchmark)
- Breaches of anti-money-laundering laws
- Charging customers for financial advice that was never provided
Important
The Commission uncovered widespread dishonest practices, including breaches of industry codes, contractual failures, and widespread customer mistreatment. It found significant governance problems at senior levels in financial institutions and revealed how ASIC had failed to adequately regulate the industry.
The Royal Commission concluded that current laws and regulations were broadly appropriate but provided 54 recommendations. The government committed to implementing all but one by the end of 2020. Key changes included:
- Requiring mortgage brokers to act in borrowers' best interests
- Extending consumer protection laws to more financial products
- Requiring APRA and ASIC to apply regulations more strictly and impose harsher penalties
The government described its response as the most significant reforms to financial services since the 1990s. Despite these issues, Australia's financial system remains globally respected - the World Economic Forum's 2017-18 Global Competitiveness Report rated Australia's banking system sixth out of 137 countries.
The four Australian regulators in detail
Reserve Bank of Australia (RBA)
The Reserve Bank of Australia is Australia's central bank. Unlike commercial banks, it does not seek to make profit or deal with ordinary customers. Instead, its primary purpose is managing the financial system to achieve the government's economic objectives.
Note
What is a central bank?
A central bank typically executes monetary policy on behalf of government, prints banknotes, and regulates the banking system. The RBA was created in 1959 under the Reserve Bank Act 1959. Before this, limited central banking operations were conducted by the Commonwealth Bank.
Charter and objectives:
According to its charter, the RBA must be guided by three broad objectives:
- The stability of Australia's currency
- The maintenance of full employment
- The economic prosperity and welfare of the people of Australia
In practice, the RBA's highest priority in recent years has been sustaining low and stable inflation, which links to its goal of maintaining currency stability.
Key functions of the RBA:
1. Conducting monetary policy: This is the RBA's most important ongoing responsibility. Monetary policy involves Reserve Bank action designed to influence the cost and availability of money in the Australian economy by influencing the general level of interest rates. The aim is to achieve sustained low inflation while encouraging economic growth.
2. Maintaining systemic stability: Although APRA now handles prudential supervision of individual banks, the RBA retains responsibility for overall financial system stability. It monitors risks and developments, conducts research, and provides guidance to APRA. The RBA works to prevent financial crises through policies like the emergency funding facility created in 2015, which banks can access if desperate for cash to meet obligations (this facility has never been used). The RBA also contributes to policies requiring banks to hold a minimum proportion of their assets in very safe or "liquid" forms.
3. Controlling note issue: The RBA is the sole authority for issuing Australian currency. Note Printing Australia, a company wholly owned by the Reserve Bank, manufactures all Australian currency. The volume of notes and coins issued varies with community demand for cash, which increases at certain times of year (such as Chinese New Year and Christmas).
4. Regulating the payments system: The RBA ensures the efficiency of payment methods including credit cards, electronic cash, travellers' cheques, and stored-value cards. It promotes stability in clearing and settling large transactions in financial markets. The Payments Systems Board within the Reserve Bank carries out these functions.
5. Acting as banker to the banks: Banks hold exchange settlement accounts with the Reserve Bank. These accounts enable banks to settle debts between themselves and with the Reserve Bank at the end of each trading day. Banks also use these accounts to buy and sell government securities from the RBA.
6. Managing Australia's reserves: The RBA holds Australia's reserves of gold and foreign currency. These reserves provide funds for international payments and for Reserve Bank operations in the foreign exchange market. The RBA also oversees dealers in the foreign exchange market.
7. Providing banking services and advice to government: The Reserve Bank provides banking and financial agency services to the Commonwealth Government and some state governments. The government can deposit excess funds with the Reserve Bank and complete transactions such as welfare and pension payments. The RBA also provides financial and economic advice to government. Its regular publications and assessments of the economy and financial markets are highly respected and significantly influence economic policymaking.
Australian Prudential Regulation Authority (APRA)
APRA provides prudential regulation for all authorised deposit-taking institutions (ADIs). ADIs include banks, credit unions, building societies, superannuation funds, and insurance companies.
Prudential regulation focuses on ensuring financial institutions remain financially sound and can meet their obligations to customers. APRA has two main regulatory roles:
1. Promoting sound institutional behavior: APRA encourages behavior by institutions that ensures they can meet their obligations to depositors, policyholders, and superannuation fund members. Essentially, APRA regulates to ensure:
- Depositors can withdraw their money when needed
- Insurance companies can meet their policy obligations
- Superannuation funds perform well and can pay members who withdraw savings
Note
APRA requires deposit-taking institutions to maintain certain levels of funds and manage risks according to specific financial models. For example, banks must hold sufficient capital relative to the riskiness of their lending.
2. Managing institutional failures: When ADIs, insurance companies, or superannuation funds experience financial difficulty, APRA intervenes to sort out the institution's financial position. Its goal is ensuring policy or deposit-holders receive as much of their funds as possible. APRA has extensive investigative powers and can intervene in any related institution if it becomes financially unviable.
Australian Securities and Investments Commission (ASIC)
ASIC regulates Australian companies and financial markets, aiming to protect investors and consumers while improving financial system performance. It monitors, investigates, and acts where the financial system's integrity has been undermined by illegal acts or unethical investment products. ASIC also protects consumers against misleading, deceptive, or unconscionable conduct affecting financial products and services.
ASIC's role is critical for lifting corporate behavior standards and maintaining financial market confidence. Specific offences ASIC regulates include:
- Insider trading: When company directors use non-public company information to buy and sell shares for profit
- Failure to disclose: When company executives fail to inform the market of price-sensitive information
ASIC typically has hundreds of investigations underway simultaneously. Each year, its legal actions result in fines for individuals and companies, frozen assets, and jail terms for major offences.
Expanded role:
In recent years, ASIC's responsibilities have expanded:
- In 2009, ASIC became the national regulator for consumer credit (home loans, personal loans, credit cards), taking over from state and territory regulators
- Since 2010, ASIC has increased responsibility for supervising security markets like the Australian Securities Exchange
Response to Royal Commission:
Important
The 2018 Banking Royal Commission criticized ASIC for trying to resolve misconduct "by agreement" rather than enforcing laws and imposing penalties. ASIC responded by:
- Recording a 20 per cent increase in investigations
- Establishing an Office of Enforcement
- Strengthening penalties for misconduct
- Adopting a "Why Not Litigate?" philosophy, signaling a harder-line enforcement approach
Important limitations:
ASIC does not prevent investors from making losses. It does not stop people investing in high-risk ventures that may fail, nor does it bail out companies experiencing financial difficulties. Instead, ASIC facilitates information flow and holds participants to standards, reflecting a view that financial markets operate most efficiently with minimum government interference.
Australian Treasury
The Australian Treasury plays an important role in financial market functioning as the main source of economic policy advice to government. Treasury influences how governments devise budgets, collect taxes, allocate expenditure, and implement policies including monetary policy, labor market policy, and market regulations.
For financial market stability specifically, Treasury:
- Provides advice on regulatory settings for financial markets, corporate practices, and consumer protection
- Keeps government informed about developments in Australian and overseas markets
- Advises on minimizing impacts of financial market disturbances on the economy
- Turns regulatory recommendations (such as those from the Royal Commission) into new laws
Note
During the global financial crisis, Treasury had a crucial role advising government on responses to market developments. Recently, Treasury has been responsible for implementing Royal Commission recommendations through new legislation.
Implementing sound economic policy and prudent financial market regulations is critical for governments to maintain long-term financial market stability.
Case study: The global financial crisis
The 2008 global financial crisis powerfully demonstrated the importance of financial market regulation. The global economy experienced its most severe financial crisis in several generations, with major financial institutions collapsing overnight, share markets crashing worldwide, and economic activity contracting into recession. Many governments took unprecedented measures to stabilize their financial systems and economies.
Origins:
The crisis originated in the mid-2000s United States, where low mortgage interest rates encouraged lending to households with higher default risk (called "subprime" borrowers). Investment banks created complicated financial instruments that packaged higher and lower risk loans together and "securitized" them for sale to other investors. When interest rates increased, mortgage defaults climbed. Financial institutions stopped lending to each other because they could not identify how exposed each was to subprime loans. Markets became volatile and credit access was restricted.
Spread through the financial system:
The US Government took over Fannie Mae and Freddie Mac, which held over half of all US mortgages ($5 trillion). Between 2007 and 2008, more than 25 major financial institutions collapsed or were bailed out, including Bear Stearns, Lehman Brothers, and American International Group. In February 2009, the United States enacted a massive $780 billion stimulus package to buy troubled assets and restore financial system stability.
Economic impacts:
The US share market lost over one-third of its value, and house prices declined by almost 20 per cent. Share markets globally fell sharply, wiping trillions of dollars off company values. Financial institutions became reluctant to lend, undermining confidence and causing falls in business investment and household consumption. In 2009, advanced economies contracted by 3.7 per cent - the first annual contraction in the global economy since World War II.
Australian experience:
Australia experienced impacts but less severe than other developed economies. While no major Australian financial institutions collapsed, the financial industry restructured, with mortgage originators being bought by traditional banks and the merging of Westpac and St George. Australia's share market lost over one-third of its peak value. Other impacts included slowing house price growth, exchange rate collapse (from over US95 cents to US60 cents in three months), commodity price falls, and economic growth slowdown.
Note
The Australian Government responded with:
- Guarantees on all bank deposits and bank overseas borrowing to improve financial market stability
- Almost $80 billion in stimulus measures to support economic activity
Lessons learned:
Before the crisis, many economists argued financial markets could self-regulate without government intervention. However, the aftermath brought widespread recognition that governments have a key role in regulating markets to underpin confidence and stability in the financial sector and broader economy.
Remember!
Summary
Key Points to Remember:
- Financial market stability is essential for economic prosperity, as instability can cause savings losses, business bankruptcies, and reduced economic growth
- Australia's financial system is regulated by four main bodies: RBA (monetary policy and systemic stability), APRA (prudential regulation of banks and financial institutions), ASIC (corporate regulation and consumer protection), and Treasury (policy advice)
- The Council of Financial Regulators coordinates activities among the four regulatory bodies to ensure effective oversight
- Australia's regulatory framework evolved through deregulation in the 1980s, Wallis Committee reforms in the late 1990s, responses to the 2008 global financial crisis, and the 2018-2019 Royal Commission
- International organizations including the Bank for International Settlements, Basel Committee, and IMF coordinate financial market regulation globally
- The global financial crisis demonstrated that financial markets require government regulation to maintain stability and protect the broader economy